
The Federal Government has called for greater investment in young people, small businesses and technology, alongside stronger public-private partnerships, to transform Nigeria from a trading economy into one driven by local production and value addition.
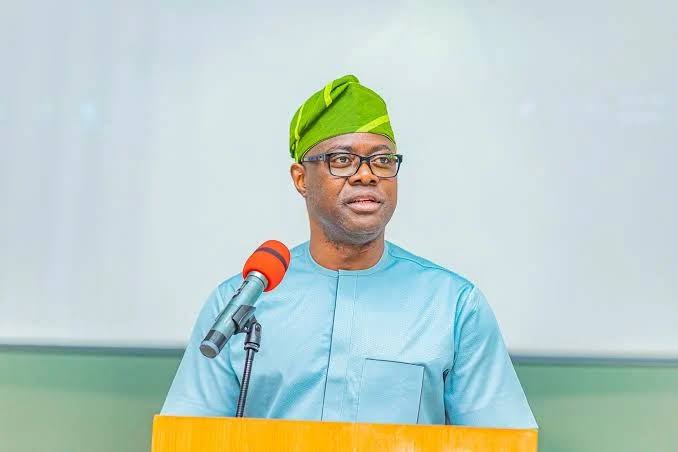
Minister of State for Foreign Affairs Sola Enikanolaiye made the call during a panel discussion titled “From Trade to Value Chains: Building Regional Industries to Compete Globally” at the 32nd Nigerian Economic Summit in Abuja. The summit was held under the theme “Growth that Works: Delivering Jobs, Productivity and Shared Prosperity,” with a sub-theme of “Invest Nigeria.”
Enikanolaiye said the government could not mobilise all the resources required for sustainable economic growth on its own, stressing the need to attract capital from both domestic businesses and foreign investors.
He said stronger cooperation between government and the private sector was essential to expand industrial capacity, create employment and improve living standards.
The minister also called for greater investment in industries capable of processing Nigeria’s raw materials into finished products for domestic consumption and export, rather than relying heavily on imports and the export of unprocessed commodities.
Investment in young people, small businesses and technology was identified as central to building a more productive economy. Expanding access to skills development, innovation and business financing could help young Nigerians participate more effectively in manufacturing, technology and other productive sectors.
Nigeria’s large youth population presents an opportunity to expand the workforce and develop new businesses, but translating that potential into economic growth requires investment in technical education, infrastructure and sustainable employment.
Former President Goodluck Jonathan recently made a similar call for greater investment in industrialisation, technical skills and local manufacturing, arguing that stronger domestic production could create jobs and reduce dependence on imported goods.
Enikanolaiye’s remarks reflect broader government efforts to encourage local processing and retain more economic value within Nigeria.
In October, Minister of Innovation, Science and Technology Kingsley Tochukwu Udeh outlined a proposed policy requiring a minimum of 30 per cent value addition to raw material exports. The proposal is intended to encourage domestic processing, industrial investment and job creation, although its implementation depends on the relevant legal and policy processes.
Developing local value chains could create opportunities for manufacturers, farmers, small businesses and technology companies while strengthening links between producers and larger markets. However, businesses will also need reliable electricity, access to finance, suitable infrastructure and consistent policies to expand production and compete internationally.
The minister stressed that mobilising investment from Nigerian businesses was as important as attracting foreign capital. Stronger partnerships, he said, would help provide the resources needed to develop industries and support shared prosperity.
The discussions at the summit come as the government seeks to convert economic reforms and investment into stronger production, employment and improved living standards.
The central challenge remains turning policy commitments into sustained investment and measurable outcomes for businesses, workers and young Nigerians.







Leave a comment